 By Nayra Roy
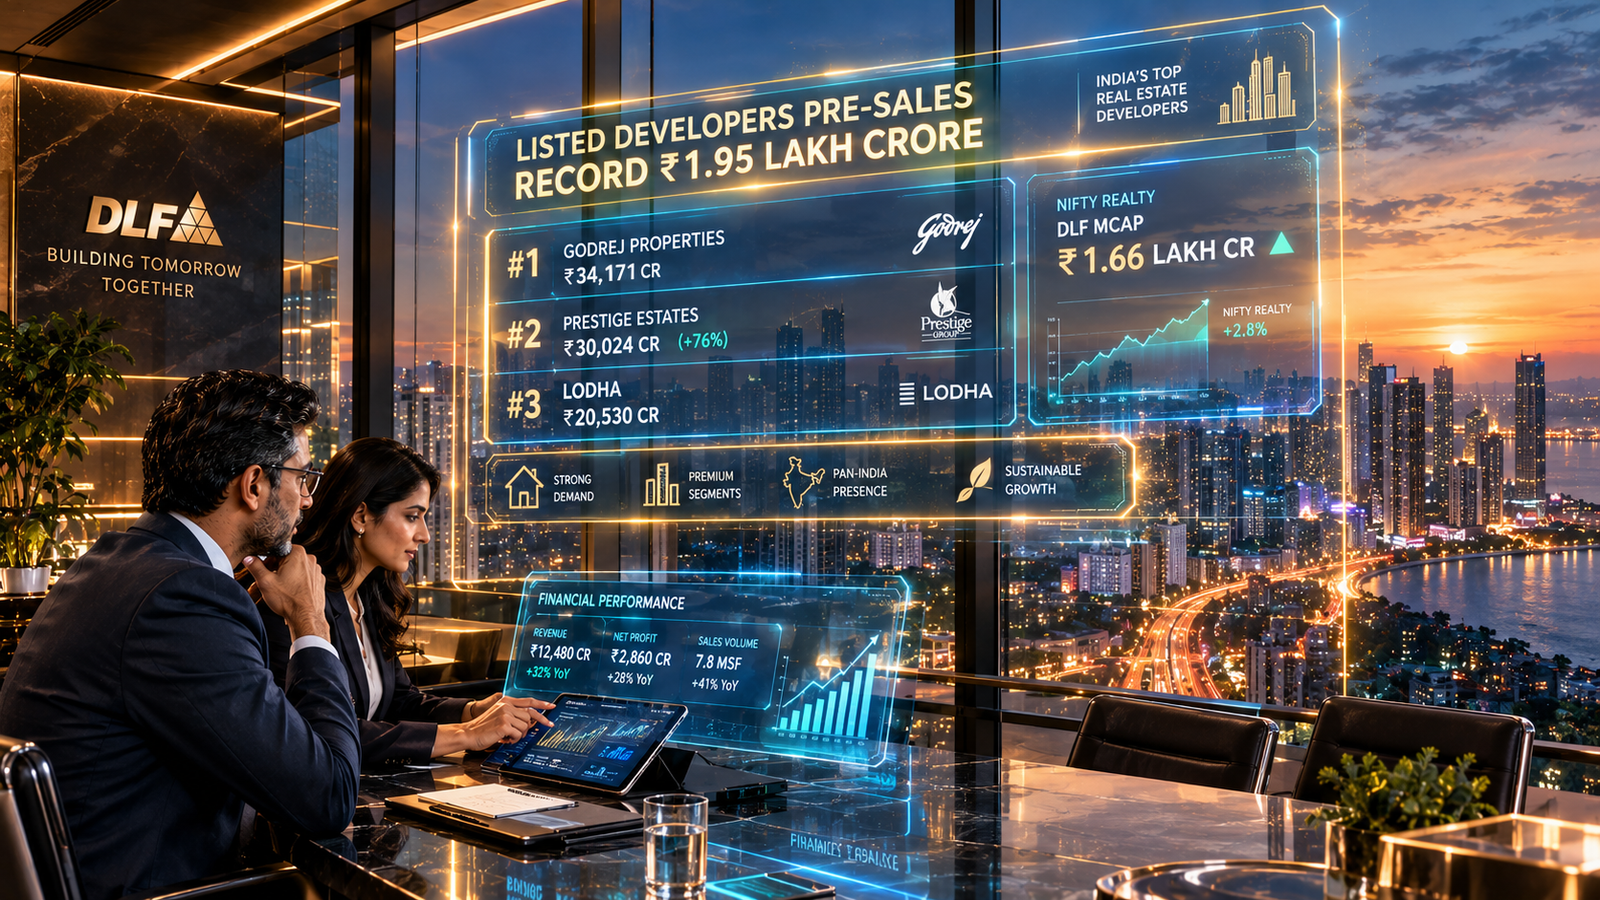
India’s real estate development landscape has completed a historic transition toward organized corporate conglomerates. Benchmark financial disclosures reveal that the country’s top 28 listed real estate companies recorded an unprecedented ₹1.95 lakh crore in cumulative sales bookings.
Consequently, listed developers pre-sales have reached historic highs, proving that homebuyers have decisively abandoned unorganized regional builders. Leading the national sales tables, Godrej Properties clocked an industry-leading ₹34,171 crore in sales bookings. Furthermore, Prestige Estates Projects jumped to second place after posting an extraordinary 76% surge in bookings to ₹30,024 crore. Therefore, institutional corporate balance sheets are dominating India’s urban redevelopment.
The Big Four Control Market Share
The pre-sales disclosures illustrate immense capital concentration among India’s top four developer brands. Together, Godrej Properties, Prestige Estates, Lodha Developers (Macrotech), and DLF accounted for over ₹1.04 lakh crore in combined bookings.
Godrej Properties achieved its milestone by selling 17,515 residential homes spanning 27 million square feet. The Mumbai Metropolitan Region contributed ₹10,313 crore to its performance, followed closely by Bengaluru with ₹8,802 crore and Delhi-NCR with ₹7,410 crore.
Meanwhile, Prestige Estates crossed the ₹30,000 crore annual threshold for the first time. Its rapid geographic expansion into Delhi-NCR and Mumbai provided growth beyond its southern base. Similarly, Lodha Developers crossed ₹20,000 crore in annual bookings for the first time.
Revenue Dominance and Market Capitalization Leaders
While Godrej Properties led the country in pre-sales bookings, other developers led on alternative financial metrics. Lodha Developers reported the highest consolidated revenue among the group at ₹16,676.2 crore, up 21% annually.
In terms of public market equity valuation, DLF remains the undisputed heavyweight with a market capitalization of roughly ₹1.66 lakh crore. Consequently, DLF commands a 20.38% weight in the Nifty Realty index, followed by Phoenix Mills at 17.05% and Lodha Developers at 15.90%.
The divergence between sales bookings and equity valuation highlights varied business models. While Godrej Properties excels at high-velocity residential sales, DLF and Phoenix Mills generate high-margin recurring rental incomes from commercial office parks and retail malls.
The Structural Moat of Institutional Developers
The continuing surge in listed developers pre-sales stems from stringent regulatory enforcement under RERA. Homebuyers refuse to risk family savings with unorganized regional builders who lack bank financing.
Listed developers secure wholesale construction debt at interest rates 300 to 500 basis points lower than unlisted peers. Furthermore, corporate developers maintain transparent escrow accounting and automated project management systems that guarantee delivery timelines.
India’s real estate sector has institutionalized permanently. By achieving ₹1.95 lakh crore in cumulative pre-sales, listed real estate giants are proving that transparent governance and financial discipline are the ultimate drivers of corporate value.
Tags: Listed Developers Pre-Sales, Godrej Properties, Prestige Estates, Lodha Developers, DLF, Nifty Realty Index, Real Estate Pre-Sales, Indian Real Estate 2026
Author CTA: Follow Flairius News — sharp takes on real estate, AI, and India’s startup economy — flairiusnews.com
 Aditya Agarwal