 By Aditya Agarwal
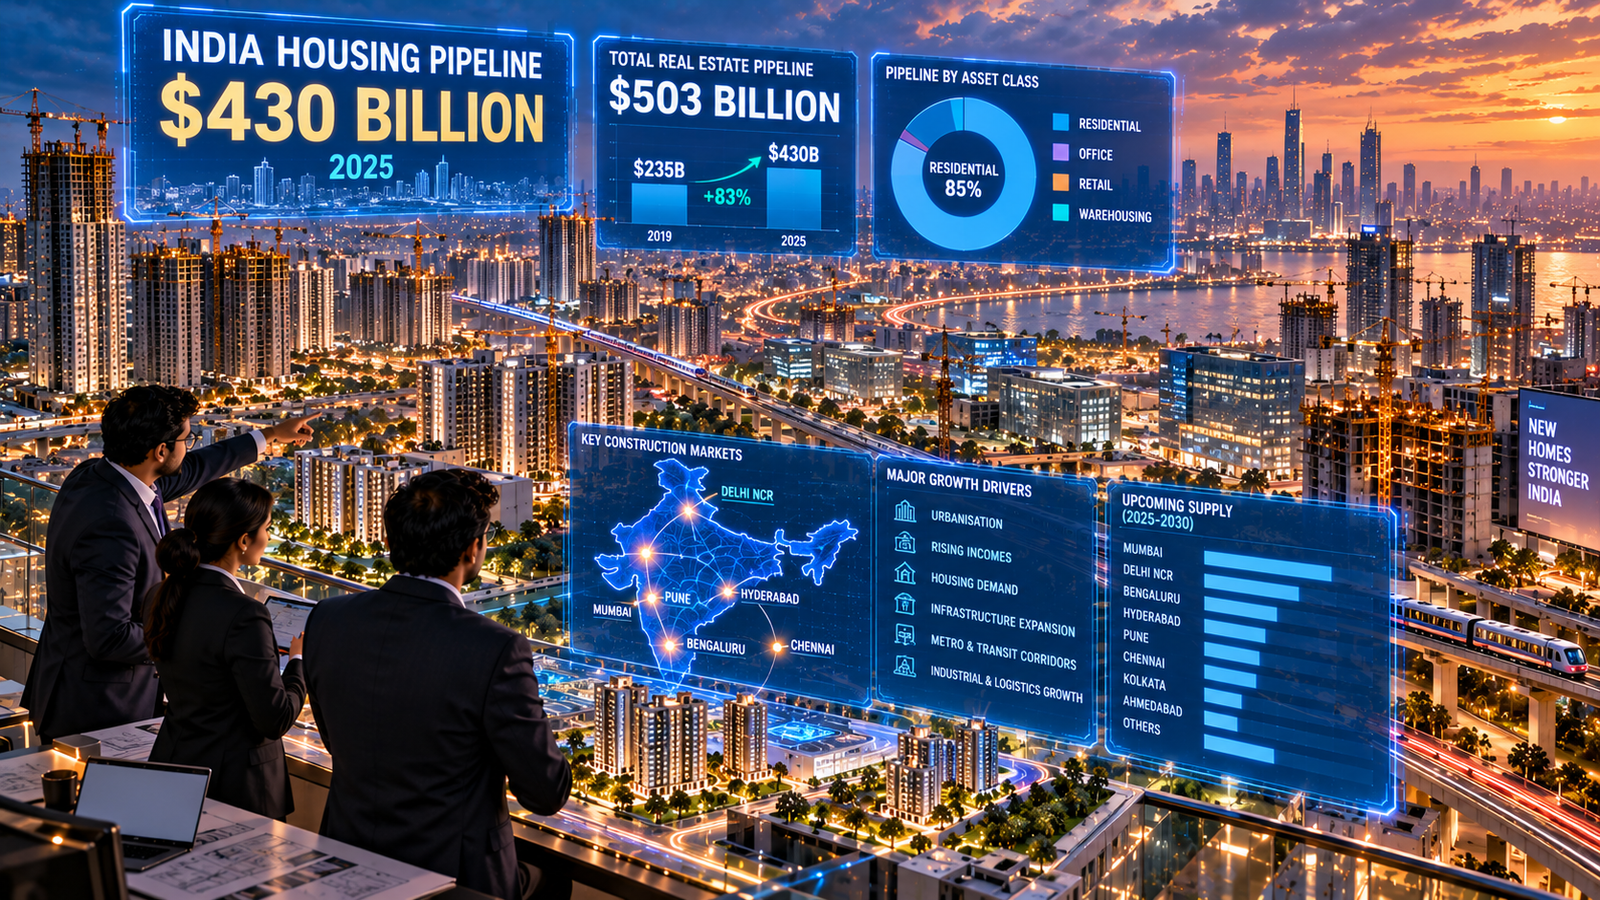
The India housing pipeline has expanded dramatically over the past several years.
Residential projects under construction were valued at approximately $430 billion in 2025, almost double the $235 billion recorded in 2019, according to a joint CREDAI-Anarock report released during CREDAI NATCON 2026.
The wider real estate construction pipeline was even larger.
Across residential, office, retail and warehousing projects, the value of property under construction reached $503 billion in 2025. That compares with only $94 billion in 2009.
Consequently, India’s property sector is moving into a much larger development cycle.
The strongest driver remains residential demand.
India Housing Pipeline Is Being Driven by Residential Demand
Residential projects represented 85% of India’s total real estate construction pipeline in 2025.
That share was only 48% in 2009.
The change highlights how strongly housing has expanded within India’s property economy.
Post-pandemic demand has played an important role.
Homebuyers have continued to support residential sales across major cities. Meanwhile, developers have responded by increasing project launches and construction activity.
Anarock chairman Anuj Puri said residential demand and office leasing have remained supportive despite geopolitical pressures. Residential sales value stayed above ₹1.3 lakh crore for seven consecutive quarters, according to the report cited by the Economic Times.
Therefore, the housing pipeline is not simply a construction statistic.
It reflects sustained demand for new residential supply.
Office Real Estate Is Still Expanding
Residential property dominates the construction pipeline.
However, commercial real estate remains important.
Office development continues to benefit from India’s Global Capability Centre expansion. According to the CREDAI-Anarock report, GCCs accounted for around 45% of total office leasing in the first half of 2026.
That creates an interesting balance.
Housing provides the majority of construction value.
Meanwhile, office demand supports the commercial side of the property market.
Warehousing is also becoming more significant.
The report said warehousing grew from a negligible base in 2009 to more than $10 billion in construction value by 2025.
As a result, India’s property cycle is becoming more diversified.
Why the $503 Billion Pipeline Matters
The scale of the broader pipeline has implications for developers, investors and financial institutions.
Construction requires substantial upfront capital.
Developers must acquire land, finance construction and manage long project cycles.
Consequently, a $503 billion pipeline represents a major demand for capital.
It also creates opportunities for construction companies, building-material manufacturers, architects, lenders and technology providers.
At the same time, such rapid expansion requires disciplined execution.
A larger pipeline does not automatically mean every project will be successful.
Location, pricing, financing and customer demand still determine project economics.
India’s Real Estate Market Is Moving Toward $1 Trillion
The CREDAI report places the broader Indian real estate market at approximately $600 billion today.
The industry body expects the market to reach $1 trillion by 2030 and almost $5.8 trillion by 2047.
Those projections illustrate the scale of the opportunity.
However, the next phase could be more complex than the previous one.
Developers will need to manage higher construction costs, financing requirements and changing buyer preferences.
Furthermore, institutional investors are increasingly focused on professionally managed assets.
That means execution quality could become as important as land availability.
The Housing Pipeline Is Becoming an Economic Indicator
India’s housing pipeline provides a useful window into the country’s broader economic expansion.
New homes require steel, cement, electrical equipment, furniture and construction labour.
Therefore, residential construction creates demand across multiple industries.
The effect extends beyond developers.
Banks finance homebuyers.
Infrastructure projects improve surrounding locations.
Retail and services follow new housing clusters.
As a result, residential construction can create a wider economic multiplier.
India’s Property Cycle Is Entering a Larger Phase
The latest CREDAI-Anarock data shows how dramatically India’s construction pipeline has expanded.
Residential projects now dominate the market.
Office leasing remains supported by GCC demand.
Warehousing is becoming a larger asset class.
Meanwhile, the total real estate construction pipeline has crossed $500 billion.
That combination suggests India’s property market is entering a scale that would have been difficult to imagine two decades ago.
The next challenge is therefore not simply building more.
It is building the right properties in the right locations with sustainable financial models.
India’s housing pipeline shows that demand is already creating the opportunity.
Now, execution will determine who captures it.
Tags: India Housing Pipeline, India Real Estate 2026, Housing Construction India, CREDAI, Anarock, Residential Real Estate, Commercial Real Estate, Property Market India
Author CTA: Follow Flairius News — sharp takes on real estate, AI, business, entrepreneurship and India’s startup economy — flairiusnews.com
 Nayra Roy